
Fifth Third: 53 Mobile Banking
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
Fifth Third: 53 Mobile Banking - Screenshots
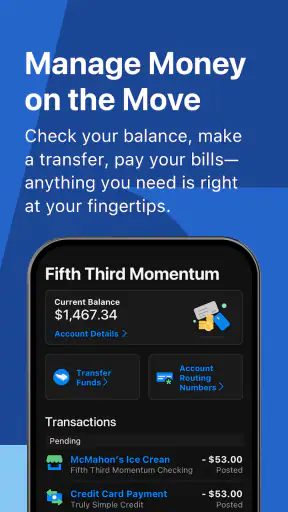
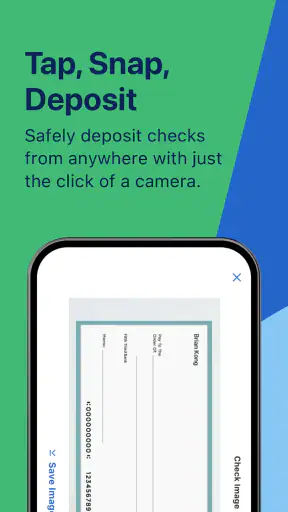
Pros
- Quick fingerprint and Face ID login on supported devices.
- Mobile check deposit saves a trip to a branch.
- Card controls help manage lost cards and spending access.
- Bill payment and transfers are conveniently available in one app.
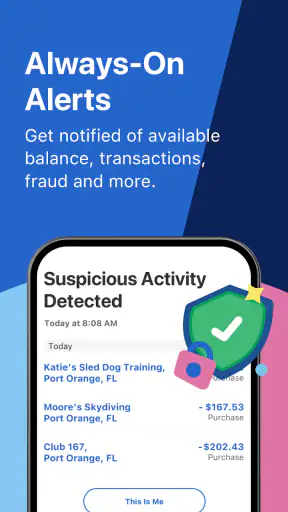
- Account alerts can help monitor balances and suspicious activity.
Cons
- Some features may require enrollment or an eligible Fifth Third account.
- Mobile check deposits can have limits and funds availability delays.
- App performance may vary during maintenance or high-traffic periods.
- Advanced budgeting and investment tools are relatively limited.
- Certain banking services may still require contacting support or visiting a branch.
Fifth Third: 53 Mobile Banking - Description
- App Name
- Fifth Third: 53 Mobile Banking
- Package Name
- com.clairmail.fth
- Developer
- Fifth Third Bank
- Category
- Finance
- Last Updated
- Nov 16, 2011
- Version
- 5.26.0
Managing a bank account from a phone sounds simple until you need to do something important while away from a branch. I tested Fifth Third: 53 Mobile Banking as a day-to-day finance app, paying attention not only to the obvious account-checking experience but also to the small decisions that determine whether a banking app actually fits someone’s routine. My overall impression is that it makes the most sense for existing Fifth Third customers who want their bank close at hand, rather than for someone comparing general-purpose money tools.
The app is free, aimed at Everyone, and developed by Fifth Third Bank. It has been available since Nov 16, 2011, and its current version is 5.26.0 for devices running OS 9 or later. With a 4.7 average from around 217 thousand ratings and over one million installs, it is clearly an established mobile-banking option rather than a new experiment. Those figures do not decide whether it is right for you, but they do suggest that the app has had time to become part of many customers’ regular banking routines.
What I would consider before choosing it
The first question is not whether the app is free. It is whether Fifth Third is already the bank you use, or the bank you are genuinely considering. A mobile banking application is closely tied to the institution behind it, so the quality of the interface cannot compensate for an unsuitable account, inconvenient branch access, or services that do not match your financial life.
I would judge this app on four practical points: how quickly I can understand my current position, how confidently I can complete routine tasks, how well it supports banking away from a computer, and whether it reduces or adds friction during stressful moments. A banking app should help me answer questions such as “Can I afford this today?” or “Has that payment gone through?” without turning a quick check into a project.
That is where the phone-based approach is useful. Instead of waiting until I am at a desktop, I can make checking my account part of the moment when the question comes up. For example, before paying for an unexpectedly expensive car repair, I would rather open a dedicated banking app and review the relevant account than rely on memory or switch between several unrelated money tools.
There is also an important distinction between a bank app and a budgeting app. A budgeting service may be better for seeing several institutions together, categorizing spending across accounts, or planning long-term goals. Fifth Third: 53 Mobile Banking is more naturally suited to managing the Fifth Third relationship itself. That narrower focus can be a strength because it keeps the experience centered on banking tasks, but it can also be a limitation for households that spread their finances across many providers.
The everyday workflow feels more valuable than the slogan
The store summary presents the idea that the bank is available whenever the phone is on. I think that message works best when translated into a specific habit: use the app for short, purposeful checks rather than treating it as a full replacement for every financial tool. I found the strongest use case in the small moments that happen several times a week—checking whether a deposit is reflected, reviewing an account before a purchase, or confirming that a transaction is where I expect it to be.
A realistic example is a busy weekday morning. I might be leaving home, notice a scheduled payment, and want to make sure the account I use for bills has enough money. With a mobile banking app, that check can happen before I leave rather than after I reach work. If the balance looks different from what I expected, I can investigate while the details are still fresh. That is a modest benefit, but repeated small checks are exactly where a banking app earns its place.
I also like the psychological separation between banking and general phone activity. A standalone finance app makes it easier to approach money deliberately instead of casually scrolling through a broader dashboard filled with unrelated notifications. For users who want a direct route into their Fifth Third accounts, that focus is more useful than a crowded financial super-app.
Useful for routine control, less useful as a complete financial command center
My view of the app changes depending on what I expect it to do. If I want a convenient mobile doorway to my Fifth Third banking relationship, it is a sensible choice. If I want a complete household financial picture that combines multiple banks, cards, investments, loans, and spending categories in one place, I would look at a broader alternative instead.
That is not a criticism of the developer’s choice to keep the app bank-centered. In fact, a narrower scope can make routine banking easier to understand. The trade-off is that I may still need another app or a spreadsheet for planning across institutions. Anyone choosing this app should decide whether that separation feels organized or inconvenient.
Another decision point is how often I need support beyond ordinary account management. A mobile app is excellent for quick access, but there are moments when a complicated dispute, account change, or sensitive question needs more than a screen. In those situations, the app may be the starting point rather than the complete solution. I would not choose any bank solely because its mobile interface looks convenient if the underlying relationship does not meet my needs.
Small habits that make the app more useful
My first practical tip is to use the app as a verification step, not only as a balance display. A balance by itself can be misleading if I forget about pending activity or recently initiated payments. Before making a large purchase, I would review the account activity and compare it with what I know I have scheduled. That habit helps distinguish “money I see” from “money I can comfortably commit.”
My second tip is to check at consistent moments instead of opening the app repeatedly without a purpose. A quick review after payday, before major bills, and after an unusual purchase creates a simple rhythm. It also makes unexpected activity easier to notice because I have a recent point of comparison. This is more effective than hoping I will remember every transaction from the week.
My third tip is to separate urgent checks from long-term analysis. If I am deciding whether I can pay for dinner, I need a clear current picture. If I am trying to understand why my spending is rising, I need a longer review and perhaps a different tool. Expecting the banking app to perform both jobs can lead to frustration. I would use Fifth Third: 53 Mobile Banking for immediate account awareness, then use a broader planning method when the question is about patterns.
A fourth useful habit is to treat the app as part of a backup routine. I would not rely on one glance at the balance before traveling or paying a large bill. I would check the account, confirm the transaction context, and keep another way to contact the bank available for situations that cannot be resolved through ordinary mobile access. This is not a flaw unique to this product; it is sensible behavior whenever money is involved.
How it compares with the usual alternatives
The closest alternative is usually a bank’s website in a mobile browser. A browser can be convenient if I rarely bank by phone or if I prefer not to install a dedicated application. However, a purpose-built app generally feels more natural for repeated checks because it is designed around the phone rather than a larger screen. For someone who only logs in occasionally, the browser may be enough. For someone who checks an account several times a week, the dedicated experience is more likely to become a useful habit.
The second alternative is a general personal-finance app. That category is often better when I need one dashboard for accounts at different institutions. It can make comparisons and overall planning easier, especially for families with complicated finances. The cost of that convenience is distance from the actual bank relationship. A third-party dashboard may be excellent for overview, while the bank’s own app remains the more direct place to manage or verify Fifth Third activity.
The third alternative is doing most banking through a branch or phone support. That may suit someone who wants personal assistance or feels uncomfortable handling financial tasks on a small screen. I would not push this app on a person who dislikes mobile banking altogether. Its value comes from making self-service convenient; if self-service is not your preferred way to bank, the convenience disappears.
Where the experience may create friction
The biggest limitation is the same thing that gives the app its focus: it is tied to Fifth Third. If I use several banks, I should expect to maintain a separate view of those other accounts. That can produce duplicated checking and more mental work. The app is not a substitute for deciding how I want to organize all my finances.
There is also the normal caution that comes with handling money on a phone. A mobile screen is convenient, but it can encourage rushed decisions. I would avoid approving or initiating anything important while distracted, especially when a transaction involves a large amount or an unfamiliar recipient. The app can make access faster, but faster access is not automatically better judgment.
Another possible source of friction is the gap between what I want to know and what a bank-centered interface is designed to show. A customer looking for detailed spending interpretation may find a dedicated banking app less satisfying than a budgeting tool. That does not make the app poor; it means the user’s question matters. “What is my current account situation?” and “What habits are driving my finances?” are different questions.
What switching really involves
If I already bank with Fifth Third, adopting the app is a relatively small behavioral switch: I am moving routine checks from a computer, branch, or phone call to a mobile screen. The real adjustment is remembering to use it deliberately. I would begin with one or two recurring checks, such as reviewing the account before bills are due, rather than trying to rebuild my entire financial routine at once.
If I do not bank with Fifth Third, the decision is much larger than downloading a free application. I would be considering a banking relationship, not merely adding a utility to my phone. That means comparing the institution’s suitability for my location, account needs, and preferred support style before the app becomes relevant. A polished mobile experience should be one part of that decision, not the deciding factor by itself.
For people moving from a broad finance dashboard, the transition may feel like losing a single overview. I would handle that by giving each tool a clear job: use the Fifth Third app for Fifth Third account awareness and use a separate method for the rest. That division can work well if I value direct banking access. It can feel tedious if I want every financial detail consolidated automatically.
Who should use it, and who should skip it
I would recommend this app to an existing Fifth Third customer who wants a straightforward way to stay connected to their accounts throughout the day. It is especially suitable for people who prefer checking their finances in short sessions rather than waiting for a monthly review. It also fits users who want the bank’s own mobile channel instead of handing their account overview to a general finance service.
I would be more cautious about recommending it to someone whose main goal is cross-bank budgeting. That person may be happier with a tool built around aggregation and long-term analysis. I would also suggest skipping it if the user is choosing a bank solely because of an app and has not considered the broader banking relationship. The application cannot make an unsuitable bank convenient in every other respect.
Families and couples should think about organization before adopting it as their only money tool. If everyone uses Fifth Third accounts, a focused bank app may be easy to understand. If finances are divided among several institutions, a second overview system may still be necessary. The best setup may be a combination rather than a single winner.
For older users or anyone worried about navigating financial technology, the Everyone age rating is reassuring in terms of intended audience, but it does not remove the need for a comfortable setup. I would help a less confident user establish a careful routine, explain what information they are checking, and avoid making the first experience a high-pressure payment or account change.
My recommendation after using it
Fifth Third: 53 Mobile Banking is a focused finance app that does its best work when I treat it as a direct connection to Fifth Third rather than as an all-purpose financial planner. Its free price makes trying it easy, and its long availability, strong average rating, and large installed base show that it has become a familiar choice for many customers. Still, popularity is not a reason to switch banks or abandon a broader budgeting system.
My clear recommendation is to use it if Fifth Third is already your bank and you want convenient, regular account awareness from your phone. Begin with simple verification habits, keep major financial decisions deliberate, and use another planning method if your finances extend beyond Fifth Third. If you need one place to analyze several institutions, a broader alternative will probably fit better. If what you want is a dependable mobile doorway to your Fifth Third accounts, this app is a practical choice that earns its place through everyday usefulness rather than unnecessary complexity.
FAQ
What is Fifth Third: 53 Mobile Banking?
Fifth Third: 53 Mobile Banking is the official mobile banking app for Fifth Third Bank customers. It lets you check account balances, review transactions, transfer money, deposit eligible checks, pay bills, manage cards, and locate nearby branches or ATMs. The app is designed to provide everyday banking access from an Android or iOS device without requiring a visit to a branch.
Is Fifth Third: 53 Mobile Banking safe to use?
The app includes standard banking security features such as encrypted connections, secure login options, alerts, and device-based authentication where supported. During testing, access required valid Fifth Third credentials, and additional verification may be requested for certain actions. Users should still install the app only from an official app store, keep their operating system updated, avoid public Wi-Fi for sensitive activity, and never share passwords or verification codes.
What can I do with the Fifth Third mobile banking app?
The app covers most routine banking tasks. You can view balances and transaction history, move money between eligible accounts, send payments, deposit checks by taking photographs, manage debit or credit card settings, receive account alerts, and search for branches or ATMs. Available features can vary depending on your account type, location, device, and Fifth Third’s current service availability.
Can I deposit checks using Fifth Third: 53 Mobile Banking?
Eligible customers can generally use the app’s mobile check deposit feature by photographing the front and endorsed back of a check, entering the amount, and submitting it for review. The images must be clear and meet the app’s instructions. Deposit limits, funds-availability schedules, endorsement requirements, and eligibility rules may apply, so users should keep the original check until the deposit is fully accepted.
Does Fifth Third: 53 Mobile Banking charge a fee?
Downloading and using the app itself is generally free for Fifth Third customers, but normal account terms and service charges may still apply. For example, fees could be associated with particular account services, transfers, overdrafts, bill-payment situations, mobile data usage, or transactions involving another institution. Review the fee schedule for your account and check with Fifth Third before using a feature with possible charges.


